Understanding the Affordable Care Act (ACA) is critical for securing financial stability and health coverage in Florida. According to recent federal data, millions of Americans rely on marketplace subsidies to afford essential medical care, with enrollment peaks occurring annually during open enrollment periods. Navigating these options requires clarity on plan tiers, subsidy eligibility, and provider networks. This guide provides the definitive framework for making informed decisions about your health insurance future. (Tax Preparation amp IRS)
Understanding the ACA Framework
The Affordable Care Act, often referred to as Obamacare, fundamentally changed how individuals and families access health insurance in the United States. It established health insurance marketplaces where consumers can compare plans side by side. These exchanges were designed to increase competition among insurers, which helps drive down costs for consumers. (Blog Quality Taxes and)
For residents of Florida, the marketplace offers a diverse array of options from major national and regional providers. The system ensures that no one is denied coverage due to pre-existing conditions. This protection is a cornerstone of the ACA and applies to all plans sold through the marketplace. Understanding the basic structure helps you avoid common pitfalls during enrollment. (Back Taxes Help Services)
Quality Taxes and Multiservices specializes in guiding clients through these complexities. We help you interpret the fine print and identify the plan that aligns with your specific health needs and budget. Our team understands the nuances of Florida's insurance landscape, ensuring you get the most value for your premium dollars.
Metal Tier Breakdown
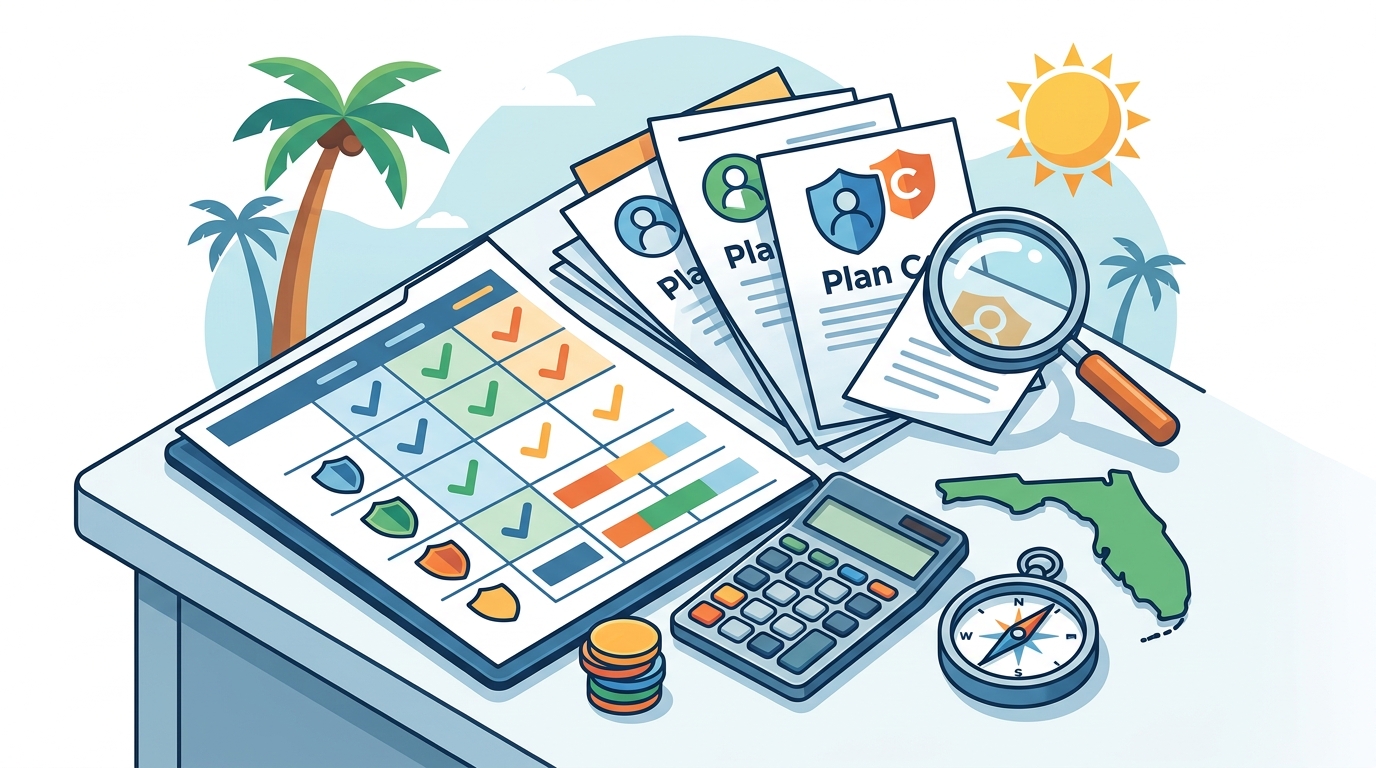
ACA plans are categorized into four metal tiers: Bronze, Silver, Gold, and Platinum. Each tier represents a different balance between your monthly premium and your out-of-pocket costs when you receive care. The tier system is standardized across all states to help consumers compare plans easily.
Bronze Plans
Bronze plans typically have the lowest monthly premiums but the highest deductibles and copayments. They are ideal for individuals who are generally healthy and rarely visit the doctor. These plans provide a safety net for catastrophic events but offer minimal coverage for routine care.
Silver Plans
Silver plans offer a middle ground with moderate premiums and moderate cost-sharing. They are often the best choice for those who qualify for cost-sharing reductions. If you receive subsidies based on your income, Silver plans may offer the most significant overall savings.
Gold and Platinum Plans
Gold and Platinum plans feature higher premiums but lower deductibles and copays. They are suitable for individuals with chronic conditions or those who anticipate frequent medical visits. These plans provide the most comprehensive coverage, reducing your financial risk during medical emergencies.
Subsidies & Tax Credits
One of the most powerful aspects of the ACA is the availability of financial assistance. Premium tax credits can significantly lower your monthly bill if your household income falls between 100% and 400% of the federal poverty level. These credits are calculated based on your expected annual income and family size.
In addition to premium subsidies, some individuals qualify for cost-sharing reductions. These reductions lower your deductibles, copayments, and coinsurance amounts. To access these benefits, you must enroll in a Silver plan through the marketplace. The IRS requires accurate income reporting to determine your eligibility for these credits.
Our team at Quality Taxes and Multiservices can help you estimate your subsidy eligibility. We ensure that your tax situation is aligned with your insurance choices to prevent surprises during tax season. Proper planning can result in substantial savings over the course of a year.
Plan Comparison Strategy
Comparing health insurance plans requires more than just looking at the monthly price. You must evaluate the total cost of care, including premiums, deductibles, and out-of-pocket maximums. Provider networks are also critical, as using out-of-network providers can lead to higher costs.
| Factor | What to Check | Why It Matters |
|---|---|---|
| Premium | Monthly cost after subsidies | Determines your baseline financial commitment |
| Deductible | Amount paid before insurance kicks in | Impacts costs for major medical events |
| Network | In-network doctors and hospitals | Ensures access to your preferred providers |
| Prescriptions | Formulary coverage for your meds | Affects cost of ongoing medication |
When evaluating plans, consider your health history and anticipated usage. If you take regular medications, check the plan's formulary to see how they are covered. If you have a preferred specialist, verify their inclusion in the network. These details can make a significant difference in your overall satisfaction with the plan.
For personalized advice, explore our Affordable Health Insurance in FL: Compare Marketplace Options guide. This resource provides deeper insights into the specific plans available in your region.
Enrollment Process
Enrolling in an ACA plan involves several steps, starting with creating an account on the marketplace website. You will need to provide personal information, including your income, household size, and citizenship status. The system will then generate a list of eligible plans and estimated subsidies.
Once you select a plan, you will complete the application and pay your first premium. Coverage typically begins on the first day of the following month. It is crucial to enroll during the open enrollment period or after a qualifying life event, such as marriage or the birth of a child.
Missing the enrollment deadline can leave you without coverage for an entire year. Our team can help you navigate this process efficiently. We ensure that all documentation is accurate and submitted on time to avoid gaps in coverage.
Key Takeaways
- The ACA provides essential protections against denial for pre-existing conditions.
- Premium tax credits are available for households earning up to 400% of the federal poverty level.
- Silver plans are often the most cost-effective option for those receiving subsidies.
- Provider networks and formularies must be checked before selecting a plan.
- Open enrollment deadlines are strict, with limited exceptions for qualifying life events.
- Quality Taxes and Multiservices offers bilingual support for diverse client needs.
- Accurate income reporting is vital for correct subsidy calculation.
Frequently Asked Questions
What is the Affordable Care Act?
The Affordable Care Act is a federal law designed to expand health insurance coverage, reduce costs, and improve the quality of care for Americans.
How do I qualify for subsidies?
You qualify for subsidies if your household income is between 100% and 400% of the federal poverty level. Your family size also plays a role in determining eligibility.
Can I enroll outside of open enrollment?
Yes, you can enroll during a Special Enrollment Period if you experience a qualifying life event, such as losing other coverage, getting married, or having a baby.
What is the difference between a deductible and a copay?
A deductible is the amount you pay out-of-pocket before your insurance starts covering costs. A copay is a fixed fee you pay for specific services, like a doctor's visit.
Does the ACA cover dental and vision?
While some ACA plans include dental and vision benefits, they are often sold as separate policies. You should check the specific details of each plan.
How do I choose between Bronze and Silver plans?
Choose Bronze if you want lower premiums and rarely use medical services. Choose Silver if you need more coverage or qualify for cost-sharing reductions.
What happens if I miss the enrollment deadline?
If you miss the deadline, you may have to wait until the next open enrollment period unless you qualify for a special enrollment period.
Can I keep my current doctor?
You can keep your current doctor if they are in the network of the plan you choose. Always verify network inclusion before enrolling.
Schedule Your Consultation
Navigating the ACA marketplace can be complex, but you do not have to do it alone. Our team at Quality Taxes and Multiservices is here to provide expert guidance and personalized support. We help you find the right plan, maximize your subsidies, and ensure seamless enrollment.
Take the first step toward financial and health security today. Contact us to schedule a consultation with a tax and insurance expert. We serve clients across Florida, New Jersey, Georgia, Texas, North Carolina, and South Carolina.